 how-to
File a Home Insurance Claim Without Raising Rates
Table of Contents
- Understanding Your Home Insurance Claim and Premium Risk
- The Home Insurance Claim Threshold: When Filing Makes Financial Sense
- When to Pay Out of Pocket for Home Repairs Instead of Filing
- How to Document Home Damage for Insurance Claims Properly
- Filing Your Claim: Steps to Minimize Rate Impact
- How Claims History and the CLUE Report Affect Your Rates
- Strategies to Protect Your Rates After Filing a Claim
- Frequently Asked Questions
Last Updated: September 27, 2026
Understanding Your Home Insurance Claim and Premium Risk
Filing a home insurance claim has financial consequences extending far beyond repair costs.
Insurers track every claim you file, and this history directly influences your future premiums. The real question is whether filing makes financial sense compared to paying out of pocket.
Your deductible is the amount you pay toward repairs before insurance kicks in. If your deductible is $1,000 and repairs cost $1,200, you receive only $200 in coverage, often less than future premium increases.
Your claims history follows you through the CLUE (Comprehensive Loss Underwriting Exchange) report, which tracks claims across all carriers. Multiple claims within a few years result in premium surcharges or non-renewal.
The Home Insurance Claim Threshold: When Filing Makes Financial Sense
A home insurance claim makes financial sense only when net reimbursement exceeds total premium increases over the years the claim remains on your record.
The Basic Break-Even Formula
-
Calculate your net reimbursement: Repair cost minus your deductible. If repairs cost $5,000 and your deductible is $1,000, your net reimbursement is $4,000.
-
Estimate your premium increase: Contact your insurer for an estimate. A first water damage claim typically increases premiums $200-$400 annually; a second claim within three years increases it $400-$600 annually.
-
Calculate the break-even period: Divide net reimbursement by estimated annual increase. If you receive $4,000 and your premium rises $300/year, you break even in 13 years.
-
Compare to your expected tenure: If you'll move or switch insurers within 5 years, a claim breaking even in 13 years is a poor financial decision.
Real-World Scenarios
Scenario 1: Small claim, high deductible
- Repair cost: $1,500 | Deductible: $1,000 | Net reimbursement: $500 | Premium increase: $200/year
- Verdict: Do not file. You'll pay $200 annually for 3-5 years, negating the $500 reimbursement.
Scenario 2: Moderate claim, standard deductible
- Repair cost: $4,000 | Deductible: $1,000 | Net reimbursement: $3,000 | Premium increase: $250/year
- Verdict: Borderline. File only if you plan to keep the policy 12+ years.
Scenario 3: Major claim, standard deductible
- Repair cost: $15,000 | Deductible: $1,000 | Net reimbursement: $14,000 | Premium increase: $400/year
- Verdict: File immediately. This is what insurance is designed for.
Factors That Change the Calculation
- Claim type: Water damage and theft trigger larger increases (15-25%) than hail or wind (5-10%).
- Claims history: A second claim within three years increases premiums 25-35% versus 10-15% for a first claim.
- Policyholder tenure: Long-term customers (10+ years) face smaller increases than newer customers.
- Local market: Premium increases vary by region and carrier; ask your agent for specifics.
- Deductible level: Higher deductibles signal lower risk and may result in smaller increases.
The Industry Rule of Thumb
Most professionals recommend filing only when repairs exceed two to three times your deductible. However, this is a starting point, not a substitute for your personal break-even calculation.
National Association of Insurance Commissioners guidance on claims
When to Pay Out of Pocket for Home Repairs Instead of Filing
Paying out of pocket makes sense for smaller losses where the claim itself creates more financial damage than the repair. Small claims are the biggest trap: a $1,500 roof leak or $800 window replacement goes on your record, affecting future rates with all insurers.
The real cost of filing includes your deductible, premium increases for 3-5 years, potential renewal difficulties, and possible coverage limitations on future claims.
Mitigation, fixing damage yourself without filing a claim, avoids CLUE report entry and future rate impact. This works best for repairs under $2,500 when you have savings, the damage is contained, and you're confident in repair quality.
Consumer Reports on insurance claim decisions
How to Document Home Damage for Insurance Claims Properly
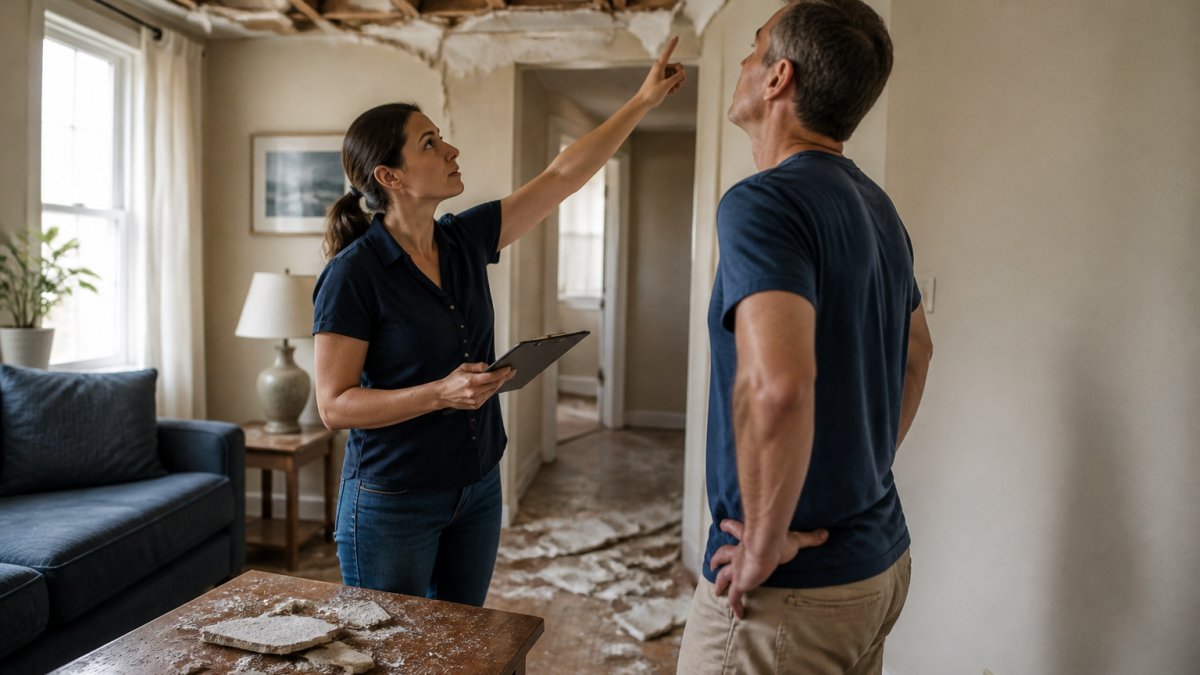
If filing makes financial sense, documentation determines your reimbursement. Start immediately: take photos and video from multiple angles, showing overall damage and close-ups of specific areas with context.
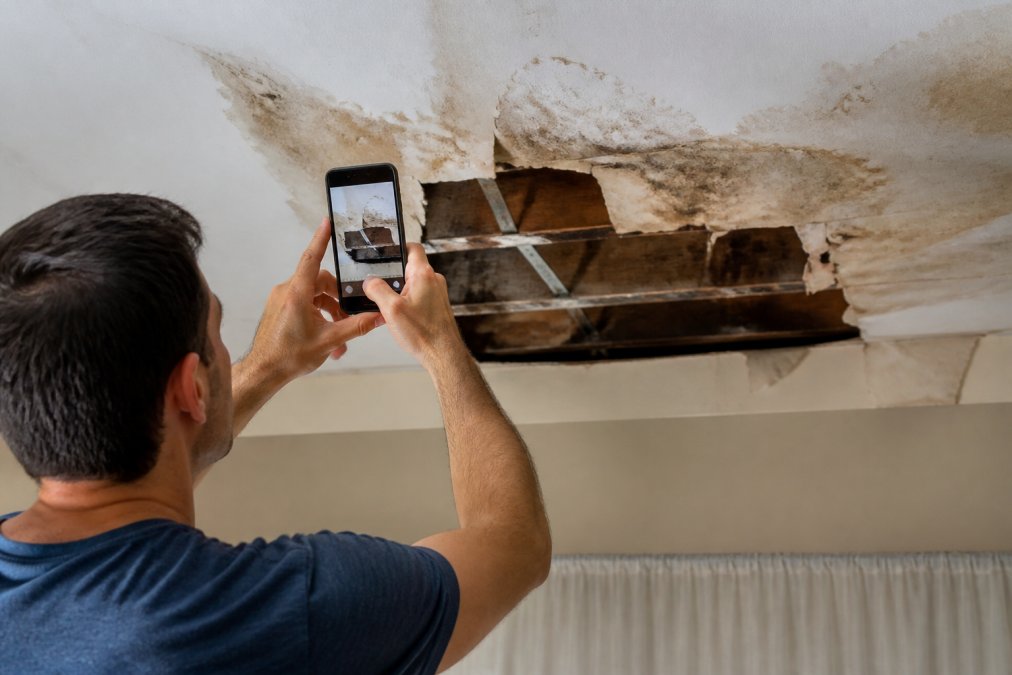
Document in writing: discovery date, cause, mitigation steps, contractor estimates, and receipts. Create an incident report with exact location, description, time, weather, and witnesses. Keep all receipts and estimates. Photograph your policy and coverage limits to prevent disputes about what was covered.
Filing Your Claim: Steps to Minimize Rate Impact
Call your insurer immediately, most policies require prompt notification. Provide complete information upfront: loss description, date/time, documentation, photos, repair estimates, and damaged items with replacement costs. Answer all adjuster questions fully. Don't accept the first settlement offer if it seems low; request re-evaluation with additional documentation. Get multiple contractor bids and choose quality work over cheap repairs.
How Claims History and the CLUE Report Affect Your Rates
Your claims history is the primary factor insurers use to predict future risk. The CLUE (Comprehensive Loss Underwriting Exchange) report tracks this history across all insurers. Understanding and managing your CLUE report is essential to protecting your rates.
What the CLUE Report Contains
The CLUE report (maintained by LexisNexis) includes all claims filed in the past 5-7 years (approved or denied), claims by previous owners (5 years), claim dates/types/amounts, insurer inquiries, and property condition issues. Critically, denied claims still appear and may be interpreted as red flags by new insurers.
How to Request and Review Your CLUE Report
You can request your CLUE report for free once per year by visiting consumer.lexisnexis.com, calling 1-866-312-8076, or mailing a written request to: LexisNexis, CLUE Consumer Disclosure Center, P.O. Box 105108, Atlanta, GA 30348. Provide your full name, current address, date of birth, and phone number. LexisNexis will mail your report within 30 days.
What to Look For in Your CLUE Report
When you receive your report, check for:
-
Accuracy of claim dates and types: Ensure all claims listed are actually yours and are correctly categorized. A water damage claim should not be listed as a theft claim.
-
Claims you don't remember filing: Sometimes claims are filed on your behalf (by a contractor or restoration company) without your explicit request. These still appear on your CLUE report.
-
Claims from previous owners: The report includes claims filed by the previous owner of your home for up to 5 years. These affect your rates even though you didn't file them. You cannot remove them, but you can explain them to your insurer.
-
Duplicate entries: Occasionally the same claim is listed twice due to data entry errors. This artificially inflates your claims history.
-
Denied claims you forgot about: You may have filed a claim that was denied years ago. It's still on your CLUE report and still affects your rates.
Disputing Inaccuracies on Your CLUE Report
If you find errors, you can dispute them:
-
Contact LexisNexis directly with documentation showing the error. For example, if a claim is listed as $5,000 but you received only $2,000, provide your settlement letter.
-
Request correction in writing: Send a dispute letter to the address above, including copies of supporting documents. LexisNexis has 30 days to investigate and respond.
-
Notify your insurer: Inform your insurance company of the dispute. Some insurers will hold off on rate increases pending the outcome of your dispute.
-
Follow up: If LexisNexis doesn't correct the error, you can file a complaint with your state's Department of Insurance.
How Claims Impact Your Rates Over Time
The CLUE report directly influences your premium. Here's the typical impact:
-
First claim: Premium increase of 10-15% for the year of the claim and the following 2-3 years. After 3-5 years, the impact fades.
-
Second claim within 3 years: Premium increase of 25-35%. Insurers now see a pattern. Some carriers will non-renew your policy after a second claim within 3 years.
-
Third claim within 5 years: Non-renewal is common. You may be forced to seek coverage in the non-standard market, where premiums are significantly higher.
-
Claims older than 5 years: These fall off your CLUE report and no longer affect your rates with new insurers. However, your current insurer may still see them in their internal records and factor them into renewal decisions.
Why Timing Matters
If you're considering filing a claim, check when your previous claims occurred.
Claims Frequency vs. Severity
When Switching Insurers Doesn't Help
LexisNexis Consumer Disclosure Center
Strategies to Protect Your Rates After Filing a Claim
Once you've filed a claim, your rate will increase. But you can take steps to minimize future damage to your rates and coverage.
Frequently Asked Questions
Will my home insurance rates go up if I file a claim?
Most claims result in a premium increase, but the amount varies based on claim type, amount, and your claims history. Minor claims under your deductible won't appear on your CLUE report and typically won't affect rates. Larger claims often trigger a surcharge of 10-25% for three to five years. The key is understanding your specific policy limits and whether the claim cost justifies the long-term premium impact. Your insurance agent can estimate the rate increase before you file.
How long do insurance claims stay on your CLUE report?
Claims typically remain on your CLUE (Comprehensive Loss Underwriting Exchange) report for five to seven years, though the impact on your premiums usually decreases after three years. Some insurers weigh recent claims more heavily than older ones. After seven years, most claims fall off completely. This is why timing matters: filing multiple claims within a short window creates a higher loss ratio, signaling increased risk to underwriters and leading to steeper rate increases.
What's the break-even point for filing a home insurance claim?
The break-even threshold depends on your deductible and expected premium increase. If repairs cost less than your deductible plus three to five years of premium surcharges, paying out of pocket typically costs less. For example, a $3,000 claim with a $1,000 deductible leaves you paying $2,000 out of pocket. If your premium increases by $300 annually for four years, that's an additional $1,200 in costs, making the total claim cost $3,200. Paying out of pocket would save $200. Always calculate the full financial impact before filing.
What documentation do I need to support a home insurance claim?
Gather photos and videos of all damage from multiple angles, your original receipts or proof of purchase for damaged items, a written list of damaged property with replacement costs, repair estimates from contractors, and any incident reports (police reports for theft or break-ins). Keep detailed records of the date, time, and cause of loss. This documentation speeds up the claims process and helps your adjuster accurately assess coverage and settlement amounts, reducing the risk of claim denial.