 how-to
Document Business Assets for Insurance: A Step-by-Step Guide
Table of Contents
- Why Documenting Business Assets Matters for Insurance
- Step 1: Create a Comprehensive Business Property Inventory
- Step 2: Use a Business Property Inventory Template to Organize Records
- Step 3: Establish Proof of Ownership for Insurance Claims
- Step 4: Determine Business Asset Valuation for Insurance
- Step 5: Document Asset Condition and Photograph Everything
- Step 6: Prepare for a Business Insurance Audit
- Step 7: Store and Update Your Records Securely
- Frequently Asked Questions
Last Updated: October 16, 2026
Why Documenting Business Assets Matters for Insurance
When disaster strikes, your claim moves fast or slow depending on one thing: how well you document business assets.
Document business assets before you need to file a claim. This protects your coverage and speeds up the claims process.
At Osime Insurance Agency, Inc, we work with business owners across industries.
Here's what most business owners miss: you don't need fancy software.
Step 1: Create a Comprehensive Business Property Inventory
Start with a simple list of everything you own that matters: equipment, furniture, electronics, tools, machinery, and stock, anything that would cost money to replace. Your inventory becomes the backbone of your claim and shows you what coverage you actually need. You can't insure what you haven't counted.
What to Include in Your Inventory
List these details for each item:
- Item name and type, be specific (not "computer" but "Dell desktop with monitor")
- Location, where in your business it sits
- Purchase date, when you bought it
- Purchase price, what you paid for it
- Current condition, working, needs repair, excellent shape
- Serial number or model number, found on the device or equipment itself
- Replacement cost estimate, what it would cost to buy new today
Don't worry about perfection on the first pass. A rough inventory beats none, and you can refine it over time.
Step 2: Use a Business Property Inventory Template to Organize Records
A business property inventory template keeps your records consistent and scannable. Here is a complete, copyable field list for Google Sheets or Excel.
The Complete Business Asset Inventory Template
Create one row per asset with these columns, covering what insurers and claims adjusters typically ask for.
| Field | What to enter | Why it matters |
|---|---|---|
| Asset ID | A short unique code (e.g., EQ-001, FURN-014) | Lets you cross-reference photos, receipts, and claim forms |
| Item name and type | Specific description (not "computer" but "Dell OptiPlex 7010 desktop with 24-inch monitor") | Prevents disputes over what was owned |
| Category | Equipment, furniture, electronics, tools, machinery, inventory, vehicles, leased assets | Groups items for policy schedules and sublimits |
| Location | Building, floor, room, or vehicle; include address if multiple sites | Supports proof of where the loss occurred |
| Serial number | Manufacturer serial or model number from the device label | Unique identifier insurers use to verify the item |
| Purchase date | Month and year (or exact date if known) | Establishes age for depreciation and ACV calculations |
| Purchase price | What you paid, in USD, before tax or with tax noted | Baseline for actual cash value and proof of ownership |
| Replacement cost estimate | What it would cost to buy new today, in USD | Supports replacement cost coverage and avoids underinsurance |
| Actual cash value estimate | Replacement cost minus depreciation | Shows the gap between RC and ACV coverage |
| Condition | New, excellent, good, fair, poor, needs repair | Documents pre-loss condition and wear |
| Proof of ownership | Receipt, invoice, credit card statement, warranty, email confirmation | Tells the adjuster where the evidence is stored |
| Photo/video reference | Filename or folder path for images | Links visual evidence to the row |
| Notes | Damage history, repairs, leased terms, warranty expiration | Captures context a spreadsheet alone misses |
| Last updated | Date you last reviewed the row | Shows the record is current |
How to Structure the Workbook
Use one tab per category if you have many items:
- Equipment and machinery, production, shop, or job-site equipment
- Furniture and fixtures, desks, shelving, signage, built-ins
- Electronics, computers, servers, phones, printers, network gear
- Tools, hand and power tools, especially those that leave the premises
- Inventory and stock, raw materials, finished goods, supplies
- Vehicles, owned and leased cars, trucks, trailers
- Leased assets, copiers, postage meters, rented equipment
- Digital assets, software licenses, data, domain names, cloud subscriptions
Add a summary tab that totals replacement cost and actual cash value by category. That total is the number you compare against your policy limits at renewal.
A Repeatable Workflow, Not a One-Time List
Treat the inventory as a cycle, not a one-time project:
- Initial pass, list every asset and fill in what you know. Rough entries are fine.
- Evidence pass, attach receipts, invoices, and photos to each high-value row.
- Valuation pass, enter replacement cost and actual cash value for each item.
- Reconciliation pass, compare category totals to your policy limits and note gaps.
- Quarterly update, add new purchases, remove disposals, and update locations.
- Annual review, refresh replacement costs and confirm coverage at renewal.
Store the file in two places: your computer and a cloud backup, so a flood or fire doesn't destroy it. Name it with a date (for example, asset-inventory-2026-Q4.xlsx) to track versions.
Step 3: Establish Proof of Ownership for Insurance Claims
Proof of ownership is what insurers ask for when you file a claim. Without it, they question whether you owned the item; with it, the claim moves forward.
Documents That Prove Ownership
Gather these for high-value items:
- Purchase receipt or invoice, shows you bought it and when
- Credit card statement, confirms the transaction date and amount
- Warranty documentation, often lists the item and serial number
- Manufacturer's box or packaging, sometimes includes purchase details
- Email confirmation, if you bought online, save the confirmation email
- Bank or accounting records, shows the expense in your business books
For lower-value items, a date-stamped photo and your inventory list often suffice; for expensive equipment, gather as much documentation as you can. Store originals in a fireproof safe, safe deposit box, or cloud storage, digital scans work as well as originals.
Step 4: Determine Business Asset Valuation for Insurance
Business asset valuation for insurance determines how much your insurer will pay if something is damaged or destroyed. Get it wrong and you're either paying for coverage you don't need or left short at claim time. Two methods matter, replacement cost and actual cash value, and the practical work is documenting both for every asset.
Replacement Cost vs. Actual Cash Value, With Worked Examples
Replacement cost is what it costs to buy the item new today, with a comparable model and current pricing. Actual cash value is replacement cost minus depreciation for age and wear.
Here is how the gap plays out on common business assets:
- Desktop computer, Bought for $1,200 three years ago. A comparable new model costs $1,000 today. Replacement cost is $1,000. If the insurer applies 40% depreciation, actual cash value is about $600. The gap is $400 per machine.
- Delivery van, Bought used for $28,000 two years ago. A comparable replacement costs $32,000 today. Replacement cost is $32,000. After depreciation, actual cash value might be $24,000. The gap is $8,000.
- Commercial oven, Bought for $9,500 five years ago. A new equivalent costs $11,000. Replacement cost is $11,000. Actual cash value after depreciation might be $6,500. The gap is $4,500.
- Office furniture, A desk bought for $800 five years ago may have a replacement cost of $900 and an actual cash value of $300. The gap is $600 per desk across the whole office.
Add those gaps across every asset and you see why valuation documentation matters: a policy paying actual cash value on a total loss may leave you tens of thousands short.
How to Document Each Value
For replacement cost, capture current market pricing, a supplier quote, a current online listing for a comparable model, or a vendor estimate, and note the date, since costs move. For actual cash value, record the purchase date and price, then note any depreciation method in your policy. Many policies publish no formula, so document age, condition, and purchase price and let the adjuster apply the schedule.
Avoid Underinsurance: Reconcile Values to Policy Limits
Underinsurance is the most common valuation mistake. It happens when your policy limit is lower than the true replacement cost of your assets. Two mechanisms cause it:
- Coinsurance clauses, Some commercial property policies include a coinsurance percentage (often 80%, 90%, or 100%). If you insure below that percentage of replacement cost, the insurer may reduce your claim payment proportionally, even for a partial loss.
- Blanket vs. scheduled limits, A blanket limit covers a pool of assets, while scheduled items are listed individually. If high-value items are not scheduled, they may hit sublimits.
Bring the Valuation to Your Agent
Document both figures in your inventory, then bring the summary tab to your agent and ask three questions:
- Does my policy pay replacement cost or actual cash value for each category?
- Are there coinsurance requirements, and does my limit meet them?
- Are high-value items scheduled, or do they fall under sublimits?
The answers tell you whether your coverage matches your actual replacement costs, so you can adjust limits before a loss rather than discover the gap during a claim.
Step 5: Document Asset Condition and Photograph Everything
Photos are your strongest evidence: they show what you owned, its condition, and identifying details like serial numbers and model numbers.
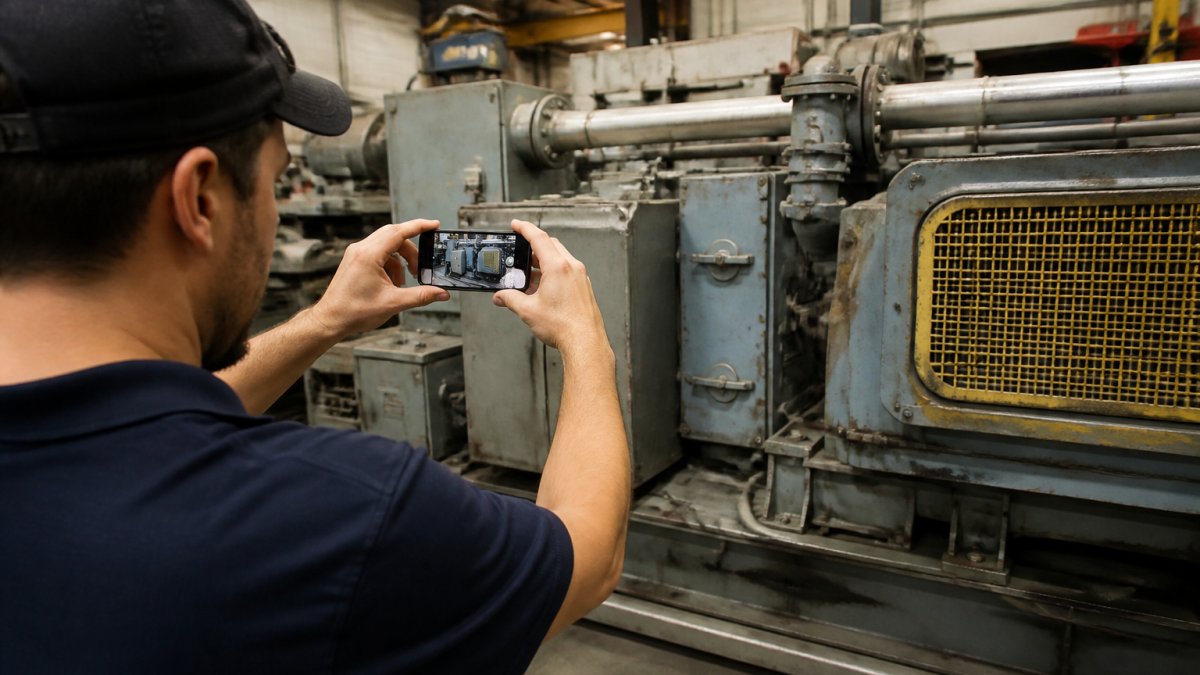
Take clear, well-lit photos of each item, with close-ups of serial numbers, model numbers, and any damage or wear.
For high-value items, shoot video. Walk around the equipment, narrate what you're looking at, and zoom in on identifying marks.
Store photos and videos in cloud backup. If your office is destroyed, your documentation survives.
Step 6: Prepare for a Business Insurance Audit
Insurers conduct audits to verify your coverage matches your actual assets and that your policy limits are accurate. Before an audit, gather your inventory spreadsheet, receipts for major purchases, and photos, and have your policy handy to reference coverage limits and exclusions.
Walk the auditor through your business, showing where equipment is located and what each asset does. If the audit reveals you're underinsured, you can increase coverage; if overinsured, you might reduce your premium. Either way, solid documentation protects you.
Step 7: Store and Update Your Records Securely
Your asset documentation is only valuable if you can find it when you need it.
Physical storage options:
- Fireproof safe at your office
- Safe deposit box at your bank
- Off-site storage facility
Digital storage options:
- Cloud backup (Google Drive, Dropbox, OneDrive)
- External hard drive stored off-site
- Email a copy to yourself
Update your inventory annually or whenever you buy equipment: add new items, remove sold or retired ones, and refresh replacement costs.
Protecting your business starts with knowing what you have.
Get your free quote from Osime Insurance Agency, Inc and let our experienced specialists review your coverage.
Frequently Asked Questions
How often should a business update its asset inventory for insurance purposes?
Update your business asset inventory at least annually, or whenever you acquire significant new equipment, machinery, or property. After major purchases, add items to your records immediately with purchase receipts and photos. Many businesses review their inventory each quarter to catch depreciation changes and ensure coverage limits match current asset values. If you file a claim, update your records after the settlement.
What's the difference between replacement cost and actual cash value for business assets?
Replacement cost is what you'd pay today to buy the same item new. Actual cash value (ACV) subtracts depreciation, so you receive less if the item is older. For example, a 5-year-old computer worth $2,000 new might have an ACV of $600. Replacement cost coverage costs more but pays the full new price. Choose based on your business needs and budget, replacement cost protects newer equipment better, while ACV suits older assets.
What documents prove ownership of business property for an insurance claim?
Keep purchase receipts, invoices, credit card statements, and bank records showing you bought the item. Include serial numbers, model numbers, and photographs of the asset. For high-value items, retain warranty documentation and proof of payment. If you inherited equipment or received it as a gift, keep a written record of the transfer. Digital records stored securely in the cloud are ideal, they survive physical damage and remain accessible during a claim.
How do I prepare my business records for an insurance audit?
Organize all asset documentation in one central location, either a digital folder or filing system. Include your inventory list, purchase receipts, invoices, photographs, and valuation records. Ensure your inventory matches your insurance policy's declared values and coverage limits. Review your records for accuracy and completeness. Have your asset list and supporting documents ready to share with your insurance company or claims adjuster. A well-organized audit file speeds up the review process and reduces claim delays.