 how-to
How to File a Comprehensive Insurance Claim
Table of Contents
- What Comprehensive Coverage Actually Covers
- Information to Gather Before Filing a Comprehensive Insurance Claim
- Step-by-Step: How to Report a Claim to Your Insurance Company
- Understanding Your Comprehensive Claim Deductible and Coverage Limits
- How Long Does a Car Insurance Claim Take
- Real Scenarios: Comprehensive Insurance Claim Examples
- Working with Your Claims Adjuster and Vehicle Inspection
- What Happens After Claim Approval and Common Delays
- Frequently Asked Questions
Last Updated: October 17, 2026
What Comprehensive Coverage Actually Covers
Comprehensive coverage is the part of your auto insurance policy that protects your vehicle from damage that isn't caused by a collision. Think of it as protection against everything except hitting another car or object.
Your comprehensive insurance claim covers losses like theft, vandalism, weather damage, animal collisions, and falling objects. Hail, wind, flooding, and fire all fall under comprehensive. So does a tree branch crashing through your windshield or a deer running into your car.
What comprehensive does NOT cover: accidents where you hit another vehicle, object, or person. That's collision coverage. Comprehensive also doesn't cover wear and tear, regular maintenance, or damage from poor upkeep.
At Osime Insurance Agency, Inc, we help clients understand exactly what their comprehensive coverage includes. Knowing the difference between comprehensive and collision prevents surprises when filing a claim.
Information to Gather Before Filing a Comprehensive Insurance Claim
Gathering the right information before you file makes the entire process faster and smoother. Your insurance company will ask for specific details, and having them ready speeds up claim approval.
Start by collecting these essentials:
- Your policy number and the date your coverage started
- The date and time the damage occurred
- Your vehicle's make, model, year, and VIN
- A description of what happened (weather event, theft, animal collision, etc.)
- Your deductible amount
- The name and contact information of any witnesses
- Your repair shop's name and contact details (if you've already gotten an estimate)
Beyond the basics, gather any documentation that proves the loss. Photos are critical. Video footage helps too. Keep receipts for any temporary repairs or emergency expenses related to the damage.
Documentation and Evidence Checklist
Evidence is what turns a claim from a conversation into a documented case. Your claims adjuster will review everything you provide to determine what your comprehensive insurance claim covers.
Document these items:
- Photos and video: Multiple angles of the damage, close-ups of broken parts, wide shots showing the scene
- Police report: Required for theft or vandalism; get the report number
- Weather records: Screenshot or print local weather data showing the storm or weather event
- Repair estimates: Get at least one written estimate from a repair shop
- Proof of ownership: Title, registration, or loan documents
- Receipts for temporary repairs: If you paid for a tarp, emergency glass repair, or similar
- Witness statements: Names and phone numbers of anyone who saw the damage
- Insurance policy: Your actual policy document showing coverage details
- Previous repair records: If your vehicle had prior damage, include those records
The more evidence you provide, the fewer questions your adjuster asks. This speeds up your comprehensive insurance claim evaluation.
Step-by-Step: How to Report a Claim to Your Insurance Company
Filing a comprehensive insurance claim involves specific steps. Following them in order prevents delays and keeps your claim moving forward.
Step 1: Contact your insurance company immediately. Call the claims department as soon as you discover the damage. Have your policy number ready.
Step 2: Provide initial details. Tell the representative the date, time, and location of the incident. Describe the damage clearly.
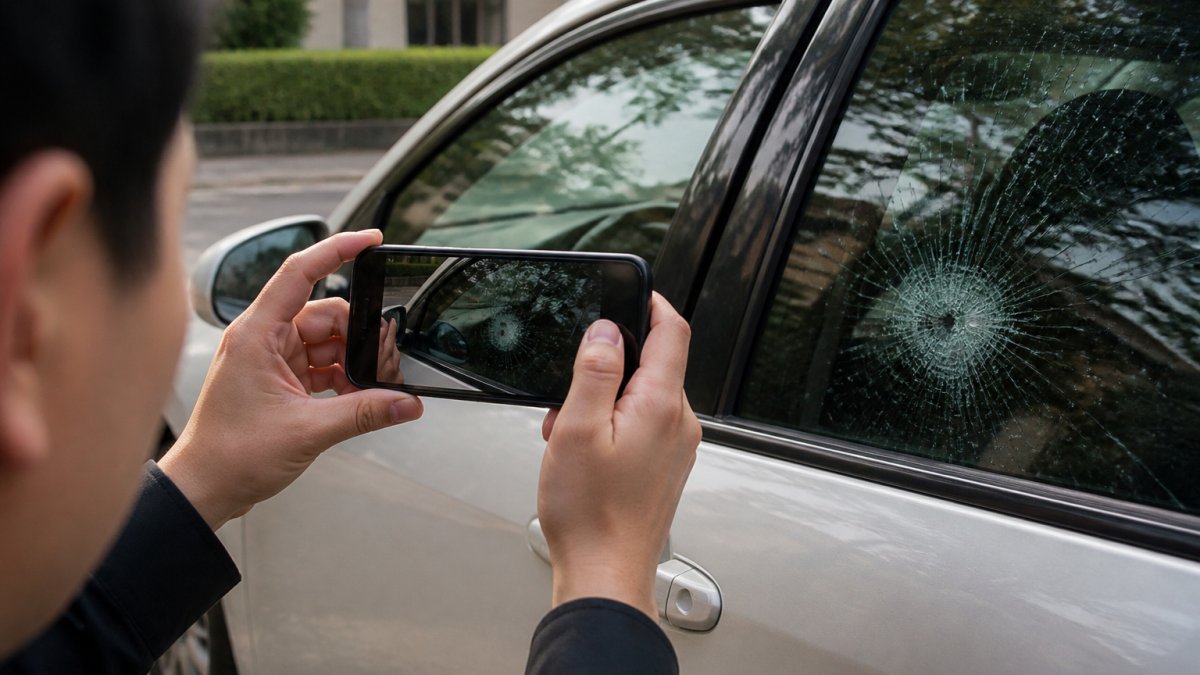
Step 3: Take photos before anything moves. Photograph the damage from multiple angles. Include wide shots and close-ups. Photograph the surrounding area if relevant.
Step 4: Document the scene. If the incident involved weather, take photos of fallen trees, hail, flooding, or other conditions.
Step 5: File the formal claim. Your insurer will send you claim forms or direct you to an online portal.
Step 6: Get a repair estimate. Contact a repair shop and request a written estimate for the damage.
Step 7: Wait for adjuster assignment. Your insurer will assign a claims adjuster to your comprehensive insurance claim.
Understanding Your Comprehensive Claim Deductible and Coverage Limits
Your deductible is the amount you pay out of pocket when you file a comprehensive insurance claim. Your insurance company pays the rest (up to your coverage limit).
Common deductibles are $250, $500, $1,000, and $2,500. A higher deductible means lower monthly premiums. A lower deductible means higher premiums but less money out of pocket when you claim.
Your coverage limit is the maximum amount your insurer will pay for a single comprehensive loss. If your limit is $15,000 and the repair costs $18,000, you're responsible for the $3,000 difference (after deductible).
Here's how the math works: If your vehicle suffers $8,000 in hail damage, your deductible is $500, and your coverage limit is $25,000, your insurance pays $7,500 ($8,000 minus $500). You pay the $500 deductible.
Review your policy to confirm your exact deductible and coverage limit. Call your agent or check your insurer's website. Knowing these numbers before damage occurs helps you make smart decisions when it does.
How Long Does a Car Insurance Claim Take
The timeline for a comprehensive insurance claim varies. Most claims take between two to four weeks from start to finish, but some take longer.
Here's the typical timeline:
- Day 1: You report the claim to your insurer
- Days 2-3: Adjuster is assigned and contacts you
- Days 3-7: Adjuster inspects the vehicle
- Days 7-14: Adjuster reviews repair estimates and approves the claim
- Days 14-21: Insurance company issues payment or repair authorization
- Days 21-28: Repairs are completed (if using insurer's preferred shop)
Weather-related claims often take longer because many people file simultaneously. Theft claims may take longer if police investigation is ongoing. Total loss claims (vehicle is totaled) can take three to six weeks.
Delays happen for several reasons. Your adjuster might need additional documentation. The repair shop might discover hidden damage during repairs. Weather can slow inspections. If you're disputing the adjuster's assessment, the process extends further.
To speed things up: respond quickly to your adjuster's requests, provide complete documentation upfront, and use a repair shop your insurer prefers (if available). Don't delay in submitting your comprehensive insurance claim paperwork.
Real Scenarios: Comprehensive Insurance Claim Examples
Understanding how comprehensive insurance claim examples work helps you know what to expect.
Theft or Vandalism Claims
Your car is parked overnight and someone breaks the window and steals your stereo. Damage: $1,200. Your deductible is $500.
What happens: You file a comprehensive insurance claim. You provide photos of the broken window and police report number. Your insurer approves the claim. You receive $700 ($1,200 minus $500 deductible). You pay the $500 deductible to the repair shop.
Weather Damage Claims
A severe hailstorm damages your vehicle's roof, hood, and windshield. Total repair cost: $5,400. Your deductible is $1,000. Your coverage limit is $30,000.
What happens: You file a comprehensive insurance claim with photos of the hail damage. Your adjuster inspects the vehicle and confirms the damage. Your insurer approves the claim. You receive $4,400 ($5,400 minus $1,000 deductible). You pay the $1,000 deductible.
Animal Collision and Other Comprehensive Losses
A deer runs into your vehicle on a rural road. Your windshield cracks, and your bumper is dented. Repair cost: $2,800. Your deductible is $250.
What happens: You file a comprehensive insurance claim. You provide photos and explain the animal collision. Your adjuster inspects the damage. Your insurer approves the claim. You receive $2,550 ($2,800 minus $250 deductible). You pay the $250 deductible.
A tree branch falls on your parked car during a windstorm. Damage: $3,100. Your deductible is $500.
What happens: You file a comprehensive insurance claim with photos showing the branch damage. Your adjuster inspects and confirms the damage was caused by the falling branch (a covered loss). Your insurer approves. You receive $2,600 ($3,100 minus $500 deductible).
Working with Your Claims Adjuster and Vehicle Inspection
Your claims adjuster is the person responsible for evaluating your comprehensive insurance claim. They inspect the vehicle, review repair estimates, and determine what your insurer will pay.
When your adjuster contacts you, have your documentation ready. Answer their questions completely and honestly. Provide photos, repair estimates, and any other evidence you've gathered.
During the inspection, the adjuster will examine the damage in person. They'll take their own photos and measurements. They'll compare the damage to your description of what happened. Be present during the inspection if possible. Point out all damage and answer questions about how it occurred.
The adjuster may ask you to get multiple repair estimates. Provide these promptly. If you disagree with the adjuster's assessment, ask them to explain their reasoning. You have the right to request a second opinion or dispute their decision.
After inspection, the adjuster writes a report recommending approval or denial of your comprehensive insurance claim. This report goes to your insurance company's claims department for final approval.
What Happens After Claim Approval and Common Delays
Once your comprehensive insurance claim is approved, your insurer issues payment or authorizes repairs.
If you're using your insurer's preferred repair shop, the shop receives authorization and begins work. You typically pay only your deductible. The insurer pays the repair shop directly.
If you're using an independent repair shop, your insurer sends you a check. You pay the deductible and use the check to pay the repair shop.
Common delays after approval include:
- Repair shop backlog: Popular shops may have a waiting list, especially after major weather events
- Hidden damage discovery: During repairs, the shop discovers additional damage not visible during initial inspection. The adjuster must approve additional payment.
- Parts availability: Specialized parts for your vehicle may be on backorder
- Weather conditions: Severe weather can delay inspections or repairs
- Documentation requests: Your insurer may ask for additional information before releasing payment
If your comprehensive insurance claim is denied, ask your insurer to explain in writing. Review your policy to understand the denial reason.
You have the right to appeal a denial. Contact your state's insurance commissioner if you believe the denial was unfair. An independent appraiser can also review the claim if you and your insurer disagree on the damage amount.
Filing a comprehensive insurance claim doesn't have to be stressful when you understand the process. At Osime Insurance Agency, Inc, we help clients navigate claims from start to finish.
Frequently Asked Questions
What information do I need to file a comprehensive insurance claim?
Gather your policy number, the date and time of the incident, location details, photos of all damage, and any police report number if applicable. For theft or vandalism, document what was stolen or damaged. For weather damage, note the weather conditions and any damage to surrounding property. Keep repair estimates from your mechanic and any receipts for temporary repairs. Your insurance agent or claims adjuster will ask for this information, so having it ready speeds up the process.
How long does a car insurance claim take from filing to payment?
Most comprehensive claims are resolved within 5 to 30 days, depending on damage complexity and claim volume. Simple claims like theft with a police report may settle faster. Weather damage claims during peak seasons can take longer. Your claims adjuster will provide an estimated timeline after the initial report. Contact your insurance company if you don't receive updates within two weeks. Some insurers offer expedited processing for total loss claims.
Do I need a police report to file a comprehensive insurance claim?
A police report is not required for all comprehensive claims, but it's strongly recommended for theft, vandalism, and animal collisions. For weather damage, hail, or falling objects, a police report is typically not necessary. However, filing a report creates an official record that supports your claim and can help prevent fraud. Contact local police non-emergency lines for property damage claims. Your insurance company will tell you if a report is required for your specific loss.
What happens after I submit my comprehensive insurance claim?
Your insurance company assigns a claims adjuster who reviews your documentation and contacts you to schedule a vehicle inspection. The adjuster assesses the damage, verifies coverage, and checks your deductible. You'll receive a claim number for reference. If approved, the insurer either pays you directly or pays the repair shop. If denied, you'll receive a written explanation. The entire process typically takes 1-4 weeks depending on damage severity and whether additional investigation is needed.