 how-to
How to Prepare for a Commercial Insurance Audit
Table of Contents
- What Is a Commercial Insurance Audit and Why Insurers Conduct Them
- Create Your Commercial Insurance Audit Checklist
- Gather Insurance Premium Audit Documents by Policy Type
- Prepare for a Workers' Compensation Premium Audit
- Understand What Happens During the Audit Process
- What Happens If You Skip an Insurance Audit
- Review Audit Findings and Dispute Errors
- Common Preparation Mistakes and How to Avoid Them
- Frequently Asked Questions
Last Updated: October 20, 2026
What Is a Commercial Insurance Audit and Why Insurers Conduct Them
A commercial insurance audit is your insurer's review of business records, payroll, employee classifications, sales revenue, to verify what you reported on your policy.
Premiums start from estimates: you provide projected payroll or revenue at purchase, and after the policy year the insurer confirms those estimates match reality.
This is standard across workers' compensation, general liability, and other commercial policies.
Create Your Commercial Insurance Audit Checklist
Start weeks before the auditor arrives. The goal: organized, accessible records that prove what you reported on your application.
Financial and General Records
Gather your general ledger and financial statements for the audit period; the auditor cross-references these against your application.
You'll need:
- General ledger for the full audit period
- Monthly or quarterly financial statements
- Income tax returns (business and personal if applicable)
Keep them in chronological order, with a spreadsheet listing what you have and where to find it.
Payroll Documentation and Employee Classifications
Payroll records are the foundation of most commercial insurance audits; workers' comp premium depends on accurate payroll totals and correct job classifications.
Prepare these documents:
- Payroll register for the entire audit period (showing employee names, hours, wages, job titles)
- Payroll tax filings (W-3s, state wage reports, quarterly filings)
- Employee records showing job titles and duties
The auditor verifies reported payroll against actual payroll.
For subcontractors, gather certificates of insurance proving they carried their own coverage and weren't classified as your employees.
Gather Insurance Premium Audit Documents by Policy Type
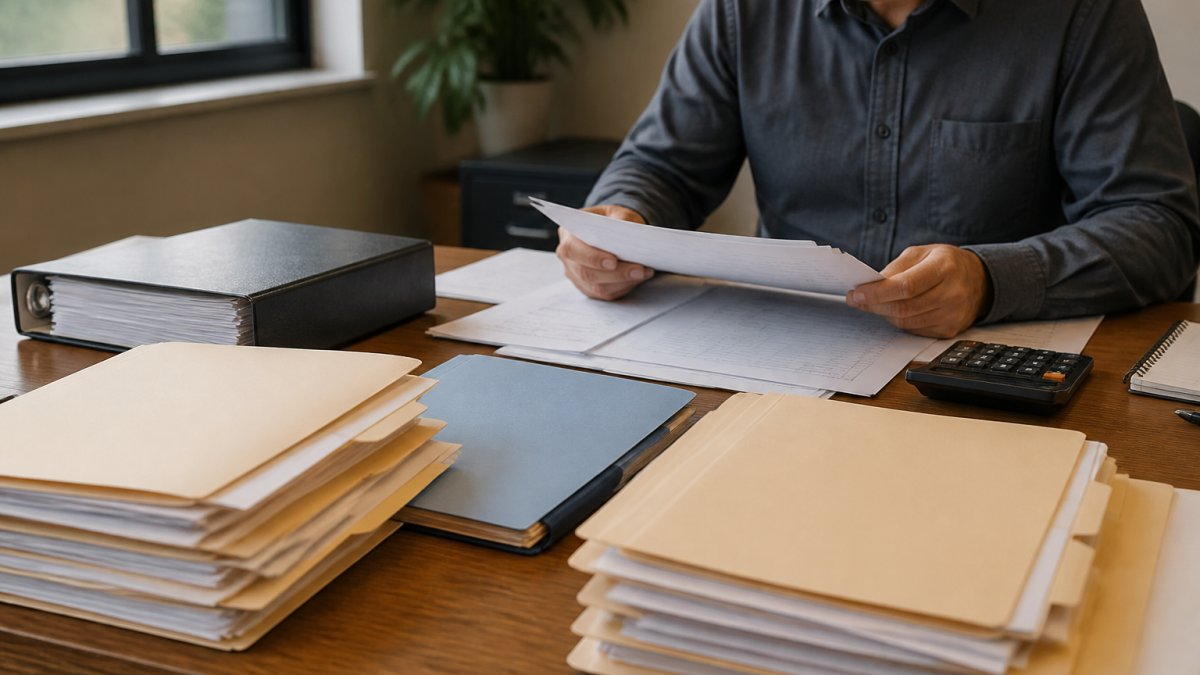
Different policies trigger different audit requirements; knowing which records matter prevents last-minute scrambling.
General Liability Policy Records
General liability audits focus on sales or revenue, since premium is often based on gross sales or contract values.
Collect these documents:
- Sales invoices or contracts for the audit period
- Sales reports or revenue summaries
- Customer contracts showing job scope and value
The auditor confirms you didn't underreport revenue. If you projected $500,000 in work but records show $750,000, premium adjusts upward to match actual exposure.
Workers' Compensation Documentation
Workers' comp audits are the most detailed, since premium is calculated on payroll dollars per classification.
Assemble:
- Complete payroll records with job classifications for each employee
- Detailed descriptions of what each job classification actually does
- Records of any employee reclassifications during the year
Misclassification is the biggest issue auditors find. Classify a roofer as a general laborer to save premium, and the auditor reclassifies them and bills the difference, often thousands.
Prepare for a Workers' Compensation Premium Audit
Workers' comp audits deserve special attention: misclassifications and payroll disputes directly increase premium, and the auditor tests every payroll dollar against your policy's classification codes. Clean results come from reconciling before the auditor asks.
Build a Classification-by-Classification Payroll Reconciliation
For every classification code on your policy, total the payroll actually paid to employees performing that work and compare it to what you reported.
Pull your payroll register for the full audit period, sort by employee, and assign each to the code matching actual day-to-day duties, not job title.
For each classification, calculate:
- Total gross wages paid (including overtime, bonuses, and commissions)
- Total overtime dollars separately, because many states allow overtime premium to be excluded from the payroll base for workers' comp premium calculation
- Total number of employees in the classification
Compare each classification total to the payroll reported on your policy.
Document What Each Classification Actually Does
The auditor verifies classifications against the rating manual's definitions. Your job is to make that comparison easy.
For each classification on your policy, assemble:
- A written job description for each employee in that classification, describing actual duties rather than a title
- Training records, certifications, or licenses that support the classification (for example, a roofer's fall-protection training or a CDL for drivers)
- Performance reviews or supervisor notes that describe the work performed
If duties changed during the year, document the date and reason; a clean paper trail prevents a reclassification dispute.
Assemble the Workers' Compensation Document Checklist
Bring these records to the audit, organized by classification:
- Complete payroll register with employee names, hours, wages, and classification codes
- Quarterly payroll tax filings (Form 941) and annual W-2s and W-3
- State unemployment wage reports, which often break out payroll by employee
Handle Subcontractor Exposure Carefully
Subcontractors are the most common source of unexpected premium in workers' comp audits: if one lacks their own coverage, the insurer may charge you premium for their payroll as if they were your employees.
For every subcontractor used during the audit period, keep:
- A current certificate of insurance showing workers' comp coverage, with the policy period covering the dates they worked
- The subcontractor's agreement or purchase order describing the scope of work
- Records of payments made to the subcontractor
A certificate that expired mid-year or lists a different entity name than the subcontractor you paid is a red flag. Verify certificates when you engage the subcontractor, not at audit time.
Calculate Your Expected Premium Before the Auditor Does
Run the premium calculation yourself: multiply each classification's payroll by its rate, apply the experience modification factor, and compare to premium paid.
If your calculation shows a credit, verify it before celebrating, it usually means you overreported payroll, often from an overly broad classification. Knowing the number in advance lets you discuss it rather than react.
Understand What Happens During the Audit Process
Insurers conduct audits remotely, by phone, or in person. Knowing which format you'll face helps you prepare.
Remote, Phone, and In-Person Audit Procedures
Remote audits run entirely through email and document submission.
Phone audits involve a scheduled call where you walk through your records while the auditor asks questions.
In-person audits happen at your location: the auditor reviews records on-site, interviews you or your staff, and may tour your facility.
Be honest during the audit. If you made a mistake on your application, disclose it.
What Happens If You Skip an Insurance Audit
Ignoring an audit notice creates serious consequences. Your insurer has the right to audit you, it's in your policy contract.
In some cases, the insurer can deny claims if you refuse to cooperate with an audit, leaving you exposed to liability you thought was covered.
The best approach is to cooperate fully and promptly: respond within the specified timeframe, submit documents on time, and answer questions honestly.
Review Audit Findings and Dispute Errors
After the audit, the insurer sends a report showing what was reviewed, what was found, and any premium adjustment. Most businesses either accept the number or panic, neither is necessary. A structured review and dispute process lets you catch errors and challenge them with evidence.
Step 1: Read the Report Line by Line
The audit report typically shows payroll by classification, the rate applied to each, the resulting premium, and the difference from what you paid. Read every line against your own records.
Check these specific items:
- Classification assignments. Did the auditor move any employee into a different classification? Compare the auditor's classification to the duties you documented.
- Payroll totals. Do the payroll figures on the report match your payroll register and your quarterly tax filings?
- Overtime treatment. If overtime premium was included in the payroll base, verify whether your state allows its exclusion.
Step 2: Identify the Specific Grounds for Dispute
A dispute is strongest when it targets a specific line item with a specific error. Vague objections ('the premium is too high') are easy to reject. Common valid grounds include:
- Misclassification. The auditor assigned a classification that does not match the employee's actual duties. Evidence: job descriptions, training records, supervisor statements, and the classification code definitions from the rating manual.
- Clerical or calculation error. A payroll total was transcribed incorrectly, a rate was applied wrong, or an employee was counted twice. Evidence: your payroll register and the auditor's worksheet side by side.
- Subcontractor certificate on file. The auditor charged premium for a subcontractor whose certificate of insurance you provided. Evidence: the certificate, the date it was sent, and proof of receipt.
Step 3: Submit a Written Dispute With Evidence
Send a written dispute to the insurer, typically to the audit department or the underwriter listed on your policy. Include:
- The audit report date and the policy number
- Each disputed line item, stated specifically
- The correction you are requesting and the dollar impact
Keep the tone factual. You are not arguing about whether the audit happened; you are pointing out specific errors and providing the records that show the correct figures.
Step 4: Escalate If Needed
If the insurer rejects your dispute or does not respond within a reasonable time, escalate. Options include:
- Asking your insurance agent or broker to intervene on your behalf, which is often the fastest path because the broker has a relationship with the underwriter
- Requesting a formal review or appeal under the insurer's internal dispute process
- Contacting your state's department of insurance to ask about complaint procedures if the dispute involves a regulatory issue
Step 5: Document the Outcome
Whatever the result, keep a record: the audit report, your dispute letter, the insurer's response, and any revised audit. If the same classification or payroll issue recurs, the prior resolution is evidence you can use.
Prevent the Next Dispute
The best dispute is the one you never have to file. After each audit, update your internal records to reflect what the auditor confirmed. If a classification was adjusted, change how you classify that work going forward. If a subcontractor certificate was missing, build a certificate-tracking step into your onboarding process.
Common Preparation Mistakes and How to Avoid Them
Most businesses make the same mistakes when preparing for audits.
Fix: Organize records now, before the audit notice arrives.
Fix: Review your classifications against the insurer's classification guide.
Fix: Report all subcontractors upfront. Get certificates of insurance from them.
Fix: Keep business and personal finances separate. Use a business bank account.
Frequently Asked Questions
What documents do I need for an insurance premium audit?
You'll need payroll records (W-2s, tax returns), employee classifications, sales and revenue reports, general ledger statements, and certificates of insurance for any subcontractors. Keep financial records organized by audit period, bank statements, check registers, and proof of any business operations changes during the policy term. The specific documents depend on your policy type, general liability, workers' compensation, and commercial insurance each require different supporting records. Contact your insurance carrier before the audit to confirm which documents they need.
How long does a commercial insurance audit typically take?
Most commercial insurance audits take 1 to 3 hours if conducted in person, though complex businesses with multiple locations or high payroll may require longer. Remote audits via phone or video can span several sessions over a few weeks as your auditor reviews documentation. The total timeline from audit notice to final premium adjustment usually ranges from 4 to 8 weeks. Organizing your records beforehand shortens the process and reduces back-and-forth requests for missing documents.
What happens if I don't complete an insurance audit?
Skipping an insurance audit can result in policy cancellation or non-renewal. Your insurance carrier may also estimate your exposure conservatively, leading to significantly higher premium adjustments than a completed audit would produce. Failure to cooperate can damage your relationship with your insurer and make it harder to obtain coverage in the future. Most carriers require audit completion as a condition of the policy, so ignoring the notice puts your business at serious financial and legal risk if an incident occurs without active coverage.
How are commercial insurance premiums adjusted after an audit?
Premiums are adjusted based on actual exposure (payroll, sales, or other metrics) versus what was reported when the policy was written. If your actual exposure was higher, you'll owe additional premium; if lower, you may receive a credit. The auditor calculates the adjustment using the audit period's financial records and employee classifications. You'll receive audit findings showing the calculation, review this carefully and ask your insurance carrier to explain any discrepancies before accepting the adjustment.
At Osime Insurance Agency, Inc, we help business owners prepare for audits and understand their coverage. Our specialists review your policies, answer questions about audit requirements, and connect you with resources to stay organized. When audit time comes, you'll have confidence that your records are ready and your coverage is accurate. Get Your Free Quote today to discuss your commercial insurance needs with our team.